Behind on payments? Owe more than your home is worth? You may qualify for a short sale.
Avoid foreclosure. Settle your mortgage for less. Start rebuilding your credit and move forward.
Over 1,000 short sales successfully negotiated in Las Vegas.
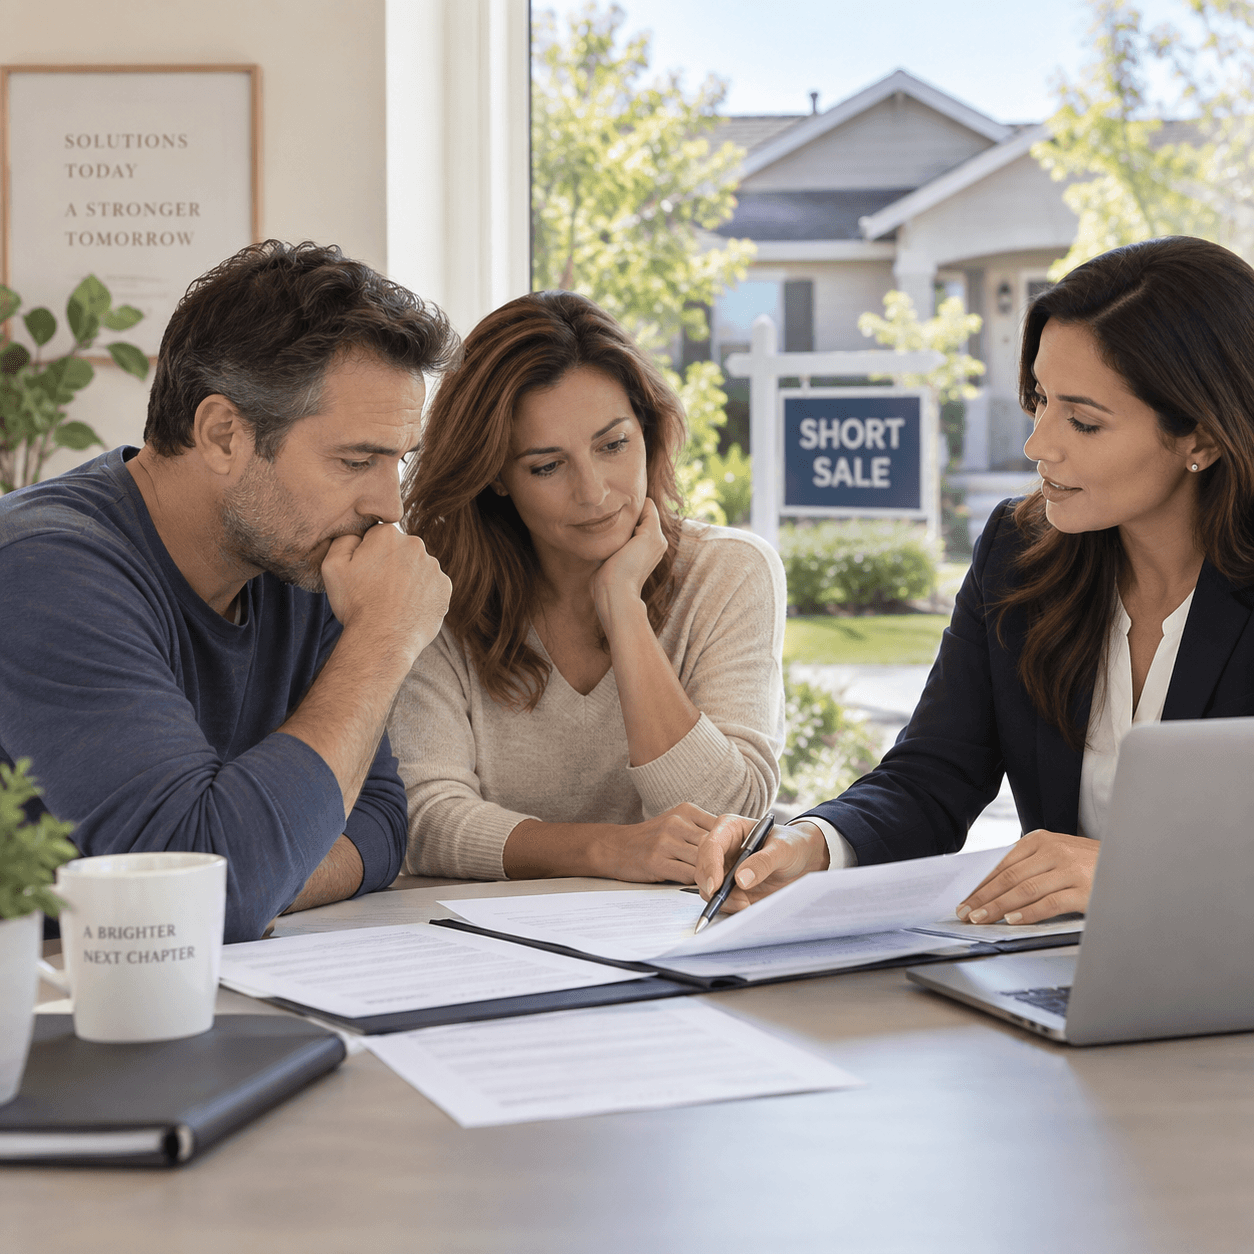
A short sale happens when your lender agrees to accept less than the full amount owed on your mortgage to settle the debt.
Instead of foreclosure, you sell the property with lender approval, resolve the debt in a structured way, and avoid the long-term consequences of a foreclosure auction.
- 01Free Confidential Consultation
- 02Hardship & Financial Review
- 03Property Listed (No Cost to You)
- 04Offer Submitted to Lender
- 05Lender Negotiation & Approval
- 06Closing & Fresh Start
You may qualify if…
- You owe more than your home is worth
- You're behind on payments or have received a Notice of Default
- You're facing foreclosure timelines
- You have a second mortgage / HELOC
- You have a solar loan or solar lien
- You've experienced hardship (job loss, divorce, medical issues)
No out-of-pocket costs. No upfront fees.
We handle the entire transaction — listing, negotiation, and closing — and the lender covers commissions in the settlement.
- The bank approves and pays the listing and buyer agent commissions
- You do not pay commissions out of pocket
- There are no upfront costs
- There are no listing fees due from you at the start
Short sales are not traditional sales — experience matters.
This is a specialized process — and when done right, it can protect your credit and help you move forward. Most agents have done fewer than 10 short sales.
Lender negotiation · 2nd liens · Solar · Timeline management · Closing coordination
- Understanding lender loss mitigation departments
- Packaging hardship documentation correctly
- Managing timelines and foreclosure pressure
- Negotiating approvals with first and second lien holders
- Resolving solar liens and subordinate liens
- Keeping buyers engaged during lender review
- Preventing approval delays that kill deals
Frequently asked questions
Will I owe money after the short sale?
Every case is negotiated individually. Many short sales result in full settlement depending on lender approval terms.
Do I have to pay real estate commissions?
No. The lender approves and pays commissions as part of the settlement. There are no upfront or out-of-pocket commissions.
Are there any upfront costs to get started?
No. There are no upfront costs. We list the home, negotiate with the bank, and get paid through the lender-approved settlement at closing.
What if I have two mortgages or a HELOC?
We negotiate with both lenders. Short sales involving first and second mortgages are common and manageable with the right strategy.
What about solar loans or solar liens?
We have experience negotiating solar-related liens and coordinating approvals so the transaction can close properly.
Can I stay in my home during the short sale process?
Yes. Most homeowners remain in the home until closing.
What if foreclosure has already started?
You may still qualify. Timing is critical — contact us immediately so we can review deadlines and options.
How long does a short sale take?
It varies by lender, but typically takes 60–120 days once an offer is submitted and the lender review begins.
Will a short sale stop foreclosure?
In many cases, yes. When properly submitted and negotiated, lenders often pause foreclosure actions while the short sale is under review.
Is this confidential?
Yes. Consultations are private and handled with discretion. We'll walk you through options without pressure.
Can I buy after a short sale?
In many cases, yes — and often sooner than after foreclosure.
FHA and Conventional loan programs have defined waiting periods. Credit repair begins immediately after closing, and we can help you map out a plan to buy again when the time is right.
This is about solving today's problem — and planning your next chapter.
Do I need an attorney?
An attorney is not required to complete a short sale. However, if you would like an attorney to review your short sale approval letter before closing, we will pay a one-time attorney review fee on your behalf.
Professional protection — without added financial pressure.
- Will I owe money after the short sale?
Every case is negotiated individually. Many short sales result in full settlement depending on lender approval terms.
- Do I have to pay real estate commissions?
No. The lender approves and pays commissions as part of the settlement. There are no upfront or out-of-pocket commissions.
- Are there any upfront costs to get started?
No. There are no upfront costs. We list the home, negotiate with the bank, and get paid through the lender-approved settlement at closing.
- What if I have two mortgages or a HELOC?
We negotiate with both lenders. Short sales involving first and second mortgages are common and manageable with the right strategy.
- What about solar loans or solar liens?
We have experience negotiating solar-related liens and coordinating approvals so the transaction can close properly.
- Can I stay in my home during the short sale process?
Yes. Most homeowners remain in the home until closing.
- What if foreclosure has already started?
You may still qualify. Timing is critical — contact us immediately so we can review deadlines and options.
- How long does a short sale take?
It varies by lender, but typically takes 60–120 days once an offer is submitted and the lender review begins.
- Will a short sale stop foreclosure?
In many cases, yes. When properly submitted and negotiated, lenders often pause foreclosure actions while the short sale is under review.
- Is this confidential?
Yes. Consultations are private and handled with discretion. We'll walk you through options without pressure.
- Can I buy after a short sale?
In many cases, yes — and often sooner than after foreclosure.
FHA and Conventional loan programs have defined waiting periods. Credit repair begins immediately after closing, and we can help you map out a plan to buy again when the time is right.
This is about solving today's problem — and planning your next chapter.
- Do I need an attorney?
An attorney is not required to complete a short sale. However, if you would like an attorney to review your short sale approval letter before closing, we will pay a one-time attorney review fee on your behalf.
Professional protection — without added financial pressure.